
08 October 2025
The European Commission has announced a further postponement of sustainability reporting obligations for large non-EU companies under the Corporate Sustainability Reporting Directive (CSRD).
Under the revised timeline, the European Sustainability Reporting Standards (ESRS) that would apply to so-called “third-country undertakings” will not be adopted until at least October 2027. The deferral is part of Brussels’ wider “simplification agenda,” which has earmarked more than 100 legislative measures for delay to ease regulatory burdens.
Originally, ESRS adoption for non-EU entities had been slated for mid-2024, but was pushed to June 2026. The latest change extends that schedule even further. The requirement had targeted foreign firms generating significant revenue in the EU-typically over €150 million in EU turnover and operating via a branch or subsidiary. The delay effectively places that requirement on indefinite hold while other reforms are debated.
This move aligns with broader efforts under the EU’s Omnibus I initiative, which is also seeking to scale back the scope and reporting obligations under CSRD and other ESG regulations. While the shift provides short-term relief for multinational companies concerned about overlapping compliance, critics warn it risks undermining transparency, weakening accountability, and creating uncertainty for global ESG investment practices.
Further ESRS third-country undertaking deferral from June 2026 to at least October 2027 - with implementation effectively on indefinite hold - represents substantial reduction in the practical extraterritorial reach of CSRD. Multinational corporates with >€150 million EU turnover had been building compliance infrastructure; the deferral provides breathing room but also creates strategic uncertainty about eventual scope.
The pattern reflects wider EU Omnibus simplification agenda. Individual regulatory reforms - CSDDD threshold increases, ESRS reduction, CBAM adjustments, non-EU ESRS deferral - collectively represent substantial recalibration of the EU's original sustainability regulatory architecture. Whether the net effect delivers more efficient or less ambitious regulation depends critically on how the pieces settle.
For non-EU multinationals with EU operations, financial institutions with cross-border operations and their compliance advisors, Cognitud's ESG strategy and transformation, sustainability due diligence and market intelligence teams help clients evaluate exposure to the shifting ESRS scope, structure sustainability-reporting capability robust across regulatory scenarios, and prepare disclosures aligned with current and prospective CSRD, ISSB and jurisdictional sustainability-reporting frameworks.
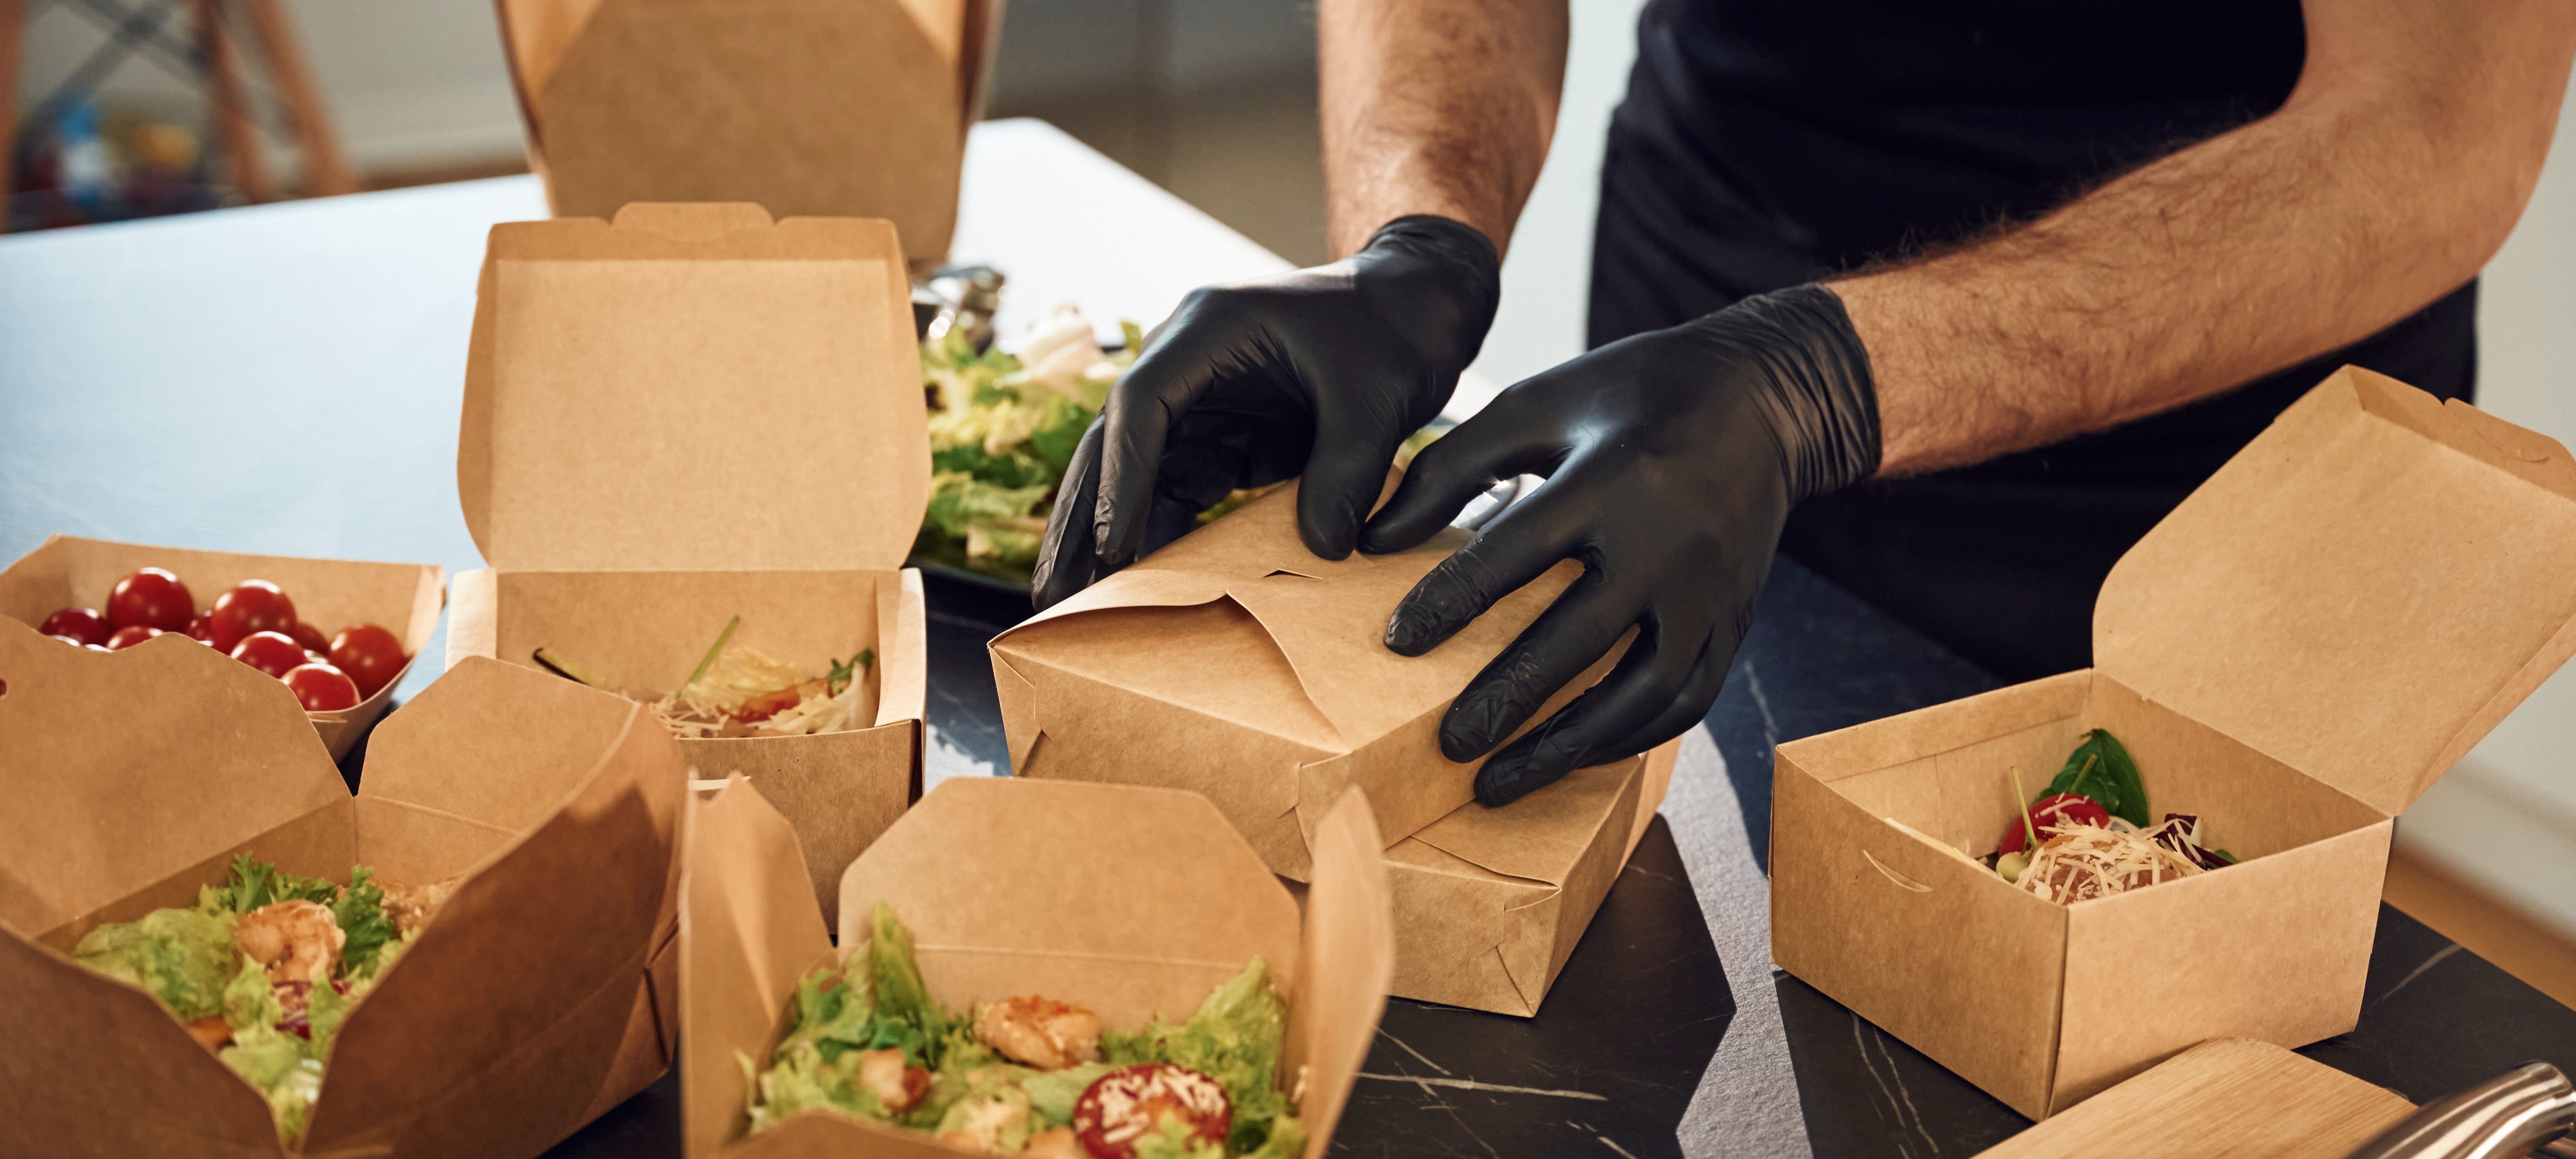
• 𝘛𝘩𝘦 𝘜𝘈𝘌 𝘍𝘰𝘰𝘥 𝘉𝘢𝘯𝘬 𝘢𝘯𝘥 𝘋𝘶𝘣𝘢𝘪’𝘴 𝘊𝘰𝘮𝘮𝘶𝘯𝘪𝘵𝘺 𝘋𝘦𝘷𝘦𝘭𝘰𝘱𝘮𝘦𝘯𝘵 𝘈𝘶𝘵𝘩𝘰𝘳𝘪𝘵𝘺 (𝘊𝘋𝘈) 𝘩𝘢𝘷𝘦 𝘴𝘪𝘨𝘯𝘦𝘥 𝘢𝘯 𝘢𝘨𝘳𝘦𝘦𝘮𝘦𝘯𝘵 𝘵𝘰 𝘤𝘰𝘭𝘭𝘦𝘤𝘵 𝘢𝘯𝘥 𝘳𝘦𝘥𝘪𝘴𝘵𝘳𝘪𝘣𝘶𝘵𝘦 𝘴𝘶𝘳𝘱𝘭𝘶𝘴 𝘧𝘰𝘰𝘥 𝘧𝘳𝘰𝘮 𝘸𝘦𝘥𝘥𝘪𝘯𝘨𝘴 𝘢𝘯𝘥 𝘦𝘷𝘦𝘯𝘵𝘴. • 𝘛𝘩𝘦 𝘪𝘯𝘪𝘵𝘪𝘢𝘵𝘪𝘷𝘦 𝘸𝘪𝘭𝘭 𝘧𝘰𝘭𝘭𝘰𝘸 𝘢𝘱𝘱𝘳𝘰𝘷𝘦𝘥…
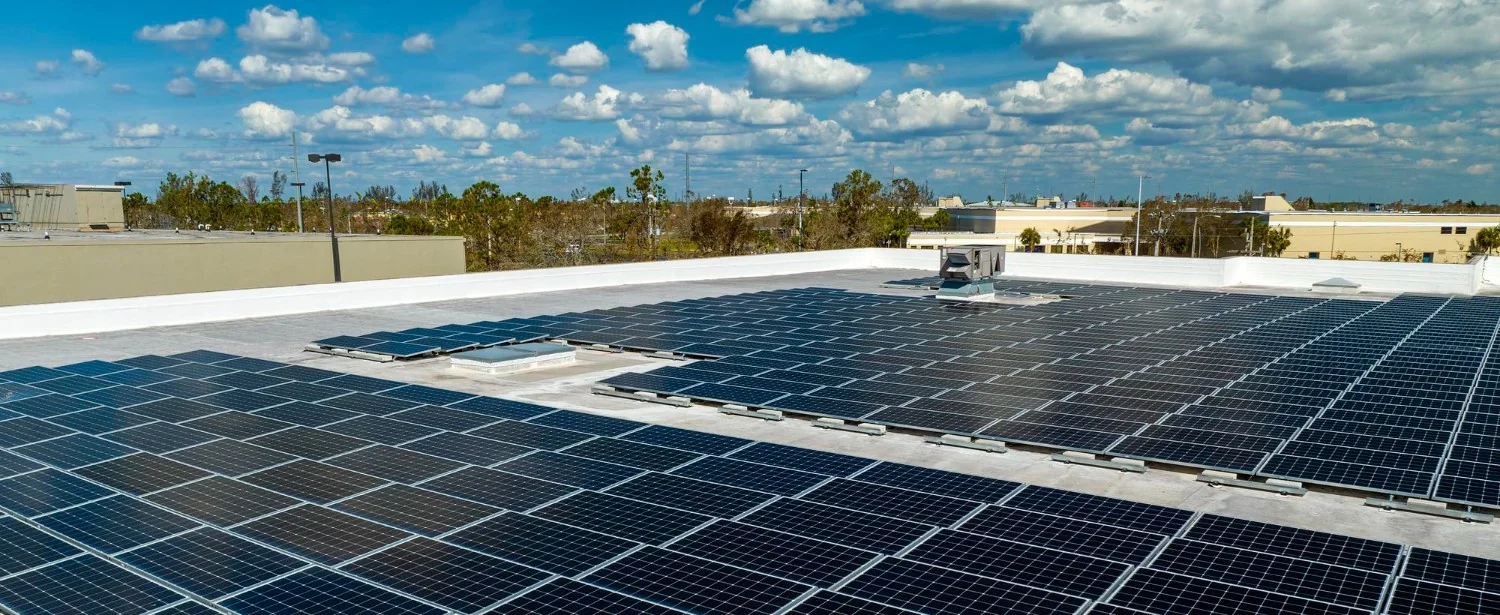
<ul><li><i>India’s rooftop solar capacity reached 30.7 GW in July 2026, increasing the need for better grid management and flexibility.</i></li><li><i>Kerala and Maharashtra are exploring battery ener…
• 𝘛𝘩𝘦 𝘌𝘐𝘉 𝘎𝘳𝘰𝘶𝘱 𝘱𝘭𝘢𝘯𝘴 𝘵𝘰 𝘱𝘳𝘰𝘷𝘪𝘥𝘦 𝘢𝘵 𝘭𝘦𝘢𝘴𝘵 €30 𝘣𝘪𝘭𝘭𝘪𝘰𝘯 𝘧𝘰𝘳 𝘤𝘭𝘪𝘮𝘢𝘵𝘦 𝘢𝘥𝘢𝘱𝘵𝘢𝘵𝘪𝘰𝘯 𝘣𝘦𝘵𝘸𝘦𝘦𝘯 2026 𝘢𝘯𝘥 2030. • 𝘛𝘩𝘦 𝘯𝘦𝘸 𝘵𝘢𝘳𝘨𝘦𝘵 𝘥𝘰𝘶𝘣𝘭𝘦𝘴 𝘢𝘥𝘢𝘱𝘵𝘢𝘵𝘪𝘰𝘯 𝘧𝘪𝘯𝘢𝘯𝘤𝘪𝘯𝘨 𝘤𝘰𝘮𝘱𝘢𝘳𝘦𝘥 𝘸𝘪𝘵𝘩 𝘵𝘩𝘦 𝘱𝘳𝘦𝘷𝘪𝘰𝘶𝘴 𝘧𝘪𝘷𝘦-𝘺𝘦𝘢𝘳 𝘱𝘦𝘳𝘪𝘰𝘥. • 𝘍𝘶𝘯𝘥𝘪𝘯𝘨…