18 August 2026
The United States has urged the European Union to make further changes to its Corporate Sustainability Reporting Directive (CSRD) and Corporate Sustainability Due Diligence Directive (CSDDD), arguing that aspects of the rules continue to create undue restrictions on transatlantic trade. The move follows commitments made under the 2025 US-EU trade framework, under which the EU agreed to work towards reducing the impact of the sustainability rules on transatlantic commerce.
The US Government has formally submitted comments on the EU's CSDDD implementation guidelines, maintaining concerns about the directive's extraterritorial reach, administrative burden and potential impact on US companies. Washington has argued that requirements affecting companies outside the EU should take greater account of equivalent regulatory frameworks in their home jurisdictions.
The pressure comes after the EU's Omnibus I simplification reforms already narrowed the scope of the CSRD and CSDDD and reduced several compliance requirements. Changes included higher thresholds for companies covered by the rules, delayed implementation timelines and a more risk-based approach to due diligence. The CSDDD's harmonised EU civil-liability regime and climate-transition-plan requirement were also removed.
Despite these changes, the US Government maintains that concerns remain, particularly regarding obligations imposed on non-EU companies and the costs associated with sustainability reporting and supply-chain due diligence. US officials have indicated that Washington could consider further measures if its concerns are not addressed.
The development adds a new dimension to the ongoing debate over the EU's sustainability regulations, as trade policy and regulatory competitiveness increasingly intersect with corporate ESG requirements. While the EU has already moved to simplify its reporting and due-diligence framework, further US pressure could influence discussions around how the rules apply to international companies and how sustainability requirements interact with global trade.
The dispute highlights the growing importance of regulatory alignment for companies operating across markets. Any further changes to the CSRD and CSDDD could affect corporate sustainability reporting, supply-chain due diligence, compliance costs and the treatment of non-EU businesses, making the ongoing EU-US discussions relevant for companies preparing for evolving sustainability requirements.
US pressure on CSRD and CSDDD scope shapes how much the EU accommodates before finalising the omnibus, and it affects what non-EU multinationals should plan for on reporting infrastructure. Our ESG-strategy and sustainability-due-diligence teams help clients build reporting infrastructure robust across omnibus scenarios.
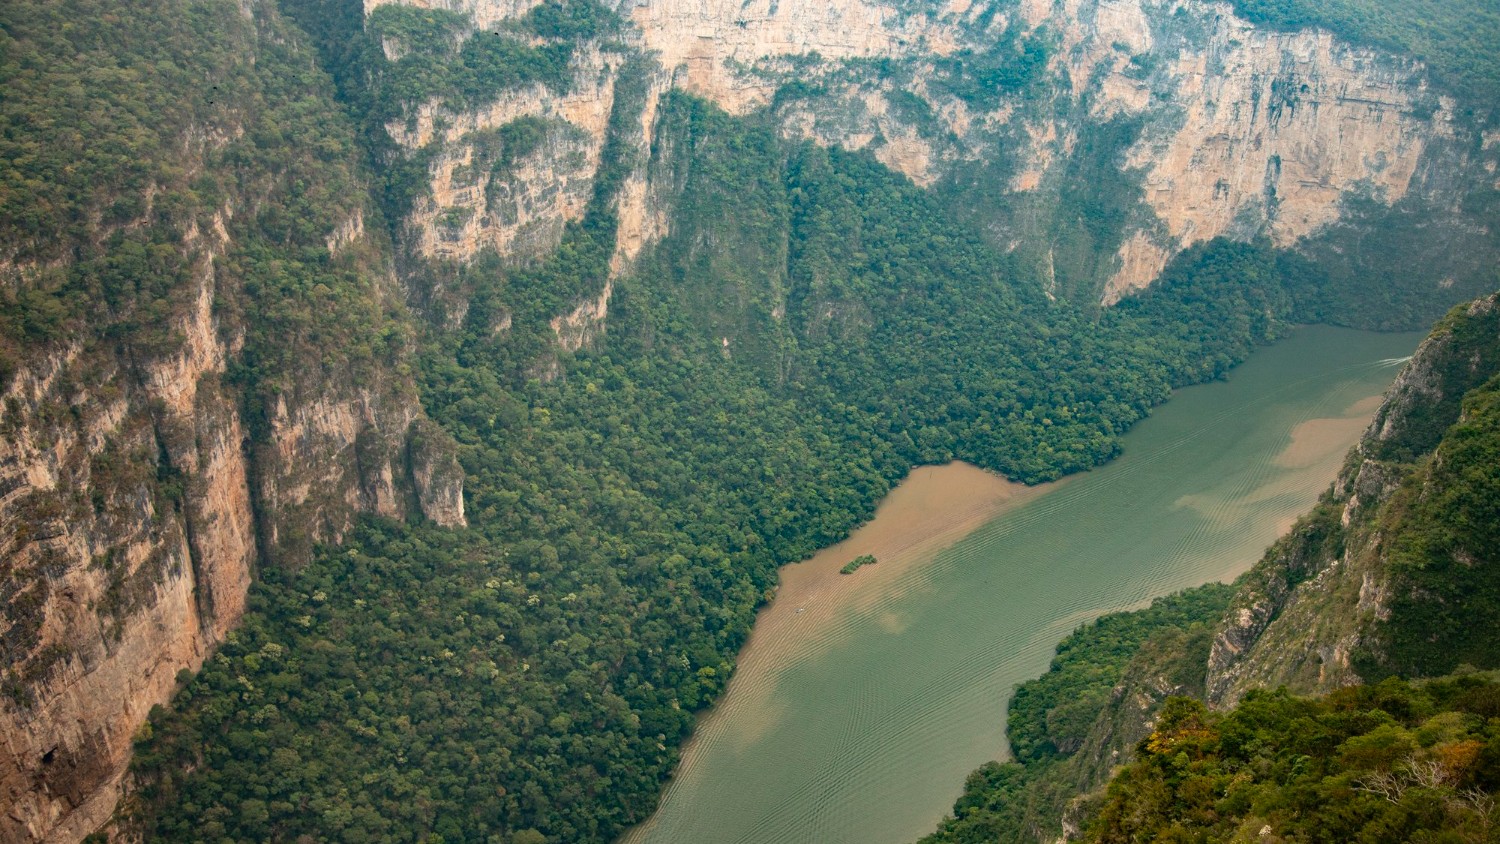
• 𝘔𝘦𝘹𝘪𝘤𝘰 𝘊𝘪𝘵𝘺 𝘩𝘢𝘴 𝘱𝘭𝘢𝘯𝘵𝘦𝘥 10 𝘮𝘪𝘭𝘭𝘪𝘰𝘯 𝘵𝘳𝘦𝘦𝘴, 𝘱𝘭𝘢𝘯𝘵𝘴, 𝘢𝘯𝘥 𝘴𝘩𝘳𝘶𝘣𝘴 𝘢𝘤𝘳𝘰𝘴𝘴 𝘤𝘰𝘯𝘴𝘦𝘳𝘷𝘢𝘵𝘪𝘰𝘯 𝘢𝘳𝘦𝘢𝘴 𝘵𝘰 𝘳𝘦𝘴𝘵𝘰𝘳𝘦 𝘦𝘤𝘰𝘴𝘺𝘴𝘵𝘦𝘮𝘴. • 𝘛𝘩𝘦 𝘤𝘪𝘵𝘺 𝘸𝘪𝘭𝘭 𝘭𝘢𝘶𝘯𝘤𝘩 𝘪𝘵𝘴 𝘭𝘢𝘳𝘨𝘦𝘴𝘵 𝘶𝘳𝘣𝘢𝘯 𝘳𝘦𝘧𝘰𝘳𝘦𝘴𝘵𝘢𝘵𝘪𝘰𝘯 𝘦𝘧𝘧𝘰𝘳𝘵, 𝘵𝘢𝘳𝘨𝘦𝘵𝘪𝘯𝘨 𝘰𝘯𝘦 𝘮𝘪𝘭𝘭𝘪𝘰𝘯 𝘢𝘥𝘥…
• 𝘕𝘰𝘳𝘸𝘢𝘺’𝘴 𝘸𝘦𝘢𝘭𝘵𝘩 𝘧𝘶𝘯𝘥 𝘮𝘢𝘯𝘢𝘨𝘦𝘳 𝘩𝘢𝘴 𝘤𝘰𝘮𝘮𝘪𝘵𝘵𝘦𝘥 $1.36 𝘣𝘪𝘭𝘭𝘪𝘰𝘯 𝘵𝘰 𝘊𝘰𝘱𝘦𝘯𝘩𝘢𝘨𝘦𝘯 𝘐𝘯𝘧𝘳𝘢𝘴𝘵𝘳𝘶𝘤𝘵𝘶𝘳𝘦 𝘗𝘢𝘳𝘵𝘯𝘦𝘳𝘴’ 𝘴𝘪𝘹𝘵𝘩 𝘧𝘭𝘢𝘨𝘴𝘩𝘪𝘱 𝘧𝘶𝘯𝘥. • 𝘛𝘩𝘦 𝘪𝘯𝘷𝘦𝘴𝘵𝘮𝘦𝘯𝘵 𝘣𝘶𝘪𝘭𝘥𝘴 𝘰𝘯 𝘢 𝘱𝘢𝘳𝘵𝘯𝘦𝘳𝘴𝘩𝘪𝘱 𝘦𝘴𝘵𝘢𝘣𝘭𝘪𝘴𝘩𝘦𝘥 𝘪𝘯 2024 𝘸𝘪𝘵𝘩 𝘢 $1.02 𝘣𝘪𝘭𝘭𝘪𝘰𝘯…
<ul><li><i>Union Cabinet approves the third phase of the Green Energy Corridor programme.</i></li><li><i>The scheme will add 51,126 circuit kilometres of transmission lines and around 229 GVA of trans…