
27 July 2026
Singapore's Accounting and Corporate Regulatory Authority (Acra) has released draft Singapore Sustainability Disclosure Standards (SSDS) for public consultation, marking a significant step towards strengthening corporate sustainability reporting. Based on the International Sustainability Standards Board (ISSB) framework, the proposed standards are tailored to Singapore's regulatory and business environment while supporting greater consistency in sustainability disclosures.
The draft introduces two reporting standards: S1, covering broader sustainability-related disclosures, and S2, focused on climate-related disclosures. Reflecting Singapore's climate-first strategy, only the S2 climate standard will be mandatory, while S1 will remain voluntary.
The proposal also includes local adaptations, such as extended relief for certain companies on Scope 3 emissions reporting and a requirement for companies to publish sustainability disclosures alongside their financial statements with an explicit statement of compliance.
Public consultation on the draft standards will run from 27 July to 25 October 2026. Once finalised, the standards are expected to strengthen transparency, improve the comparability of sustainability information, and provide businesses with greater clarity on reporting expectations. The initiative reinforces Singapore's commitment to advancing high-quality sustainability reporting while aligning with globally recognised disclosure frameworks.
The draft SSDS with S1 voluntary and S2 mandatory reflects Singapore's climate-first sequencing plus practical calibration for local market conditions. Mandatory climate disclosure aligned with ISSB S2 combined with voluntary broader sustainability disclosure aligned with ISSB S1 provides the phased-adoption architecture that first-cycle implementation typically benefits from.
The Scope 3 relief provision and financial-statement-integration requirement plus explicit compliance-statement architecture captures thoughtful implementation design. Scope 3 measurement is technically challenging particularly for smaller entities; measured relief during capability build-out is pragmatic. Financial-statement integration with explicit compliance signals to investors that sustainability information sits alongside audited-financial information.
For corporates operating in Singapore, financial institutions with Singapore-listing portfolio exposure and their compliance advisors, Cognitud's ESG strategy and transformation, sustainability due diligence and market intelligence teams help clients evaluate exposure under draft SSDS framework, structure sustainability-reporting infrastructure aligned with S2 mandatory and S1 voluntary architecture, and prepare disclosures aligned with SGX, ACRA, ISSB and jurisdictional sustainability-reporting frameworks.
• 𝘋𝘶𝘣𝘢𝘪 𝘋𝘦𝘱𝘢𝘳𝘵𝘮𝘦𝘯𝘵 𝘰𝘧 𝘌𝘤𝘰𝘯𝘰𝘮𝘺 𝘢𝘯𝘥 𝘛𝘰𝘶𝘳𝘪𝘴𝘮 𝘩𝘢𝘴 𝘢𝘸𝘢𝘳𝘥𝘦𝘥 𝘵𝘩𝘦 𝘋𝘶𝘣𝘢𝘪 𝘚𝘶𝘴𝘵𝘢𝘪𝘯𝘢𝘣𝘭𝘦 𝘛𝘰𝘶𝘳𝘪𝘴𝘮 𝘚𝘵𝘢𝘮𝘱 𝘵𝘰 237 𝘩𝘰𝘵𝘦𝘭𝘴 𝘪𝘯 𝘪𝘵𝘴 𝘭𝘢𝘵𝘦𝘴𝘵 𝘤𝘺𝘤𝘭𝘦. • 𝘛𝘩𝘦 𝘯𝘶𝘮𝘣𝘦𝘳 𝘰𝘧 𝘳𝘦𝘤𝘰𝘨𝘯𝘪𝘴𝘦𝘥 𝘩𝘰𝘵𝘦𝘭𝘴 𝘳𝘰𝘴𝘦 55% 𝘧𝘳𝘰𝘮 153 𝘪𝘯 𝘵𝘩𝘦 𝘱𝘳𝘦𝘷𝘪𝘰𝘶𝘴 𝘤𝘺𝘤𝘭𝘦 𝘢…
• 𝘔𝘦𝘹𝘪𝘤𝘰 𝘩𝘢𝘴 𝘢𝘱𝘱𝘳𝘰𝘷𝘦𝘥 55 𝘱𝘳𝘪𝘷𝘢𝘵𝘦 𝘸𝘪𝘯𝘥 𝘢𝘯𝘥 𝘴𝘰𝘭𝘢𝘳 𝘱𝘳𝘰𝘫𝘦𝘤𝘵𝘴 𝘸𝘰𝘳𝘵𝘩 𝘜𝘚$10.6 𝘣𝘪𝘭𝘭𝘪𝘰𝘯. • 𝘛𝘩𝘦 𝘢𝘱𝘱𝘳𝘰𝘷𝘦𝘥 𝘱𝘳𝘰𝘫𝘦𝘤𝘵𝘴 𝘸𝘪𝘭𝘭 𝘢𝘥𝘥 10,883 𝘔𝘞 𝘰𝘧 𝘯𝘦𝘸 𝘳𝘦𝘯𝘦𝘸𝘢𝘣𝘭𝘦 𝘨𝘦𝘯𝘦𝘳𝘢𝘵𝘪𝘰𝘯 𝘤𝘢𝘱𝘢𝘤𝘪𝘵𝘺. • 𝘗𝘳𝘪𝘷𝘢𝘵𝘦 𝘪𝘯𝘷𝘦𝘴𝘵𝘮𝘦𝘯𝘵 𝘸𝘪𝘭𝘭 𝘢𝘤𝘤𝘦𝘭𝘦𝘳𝘢𝘵𝘦 𝘔𝘦…
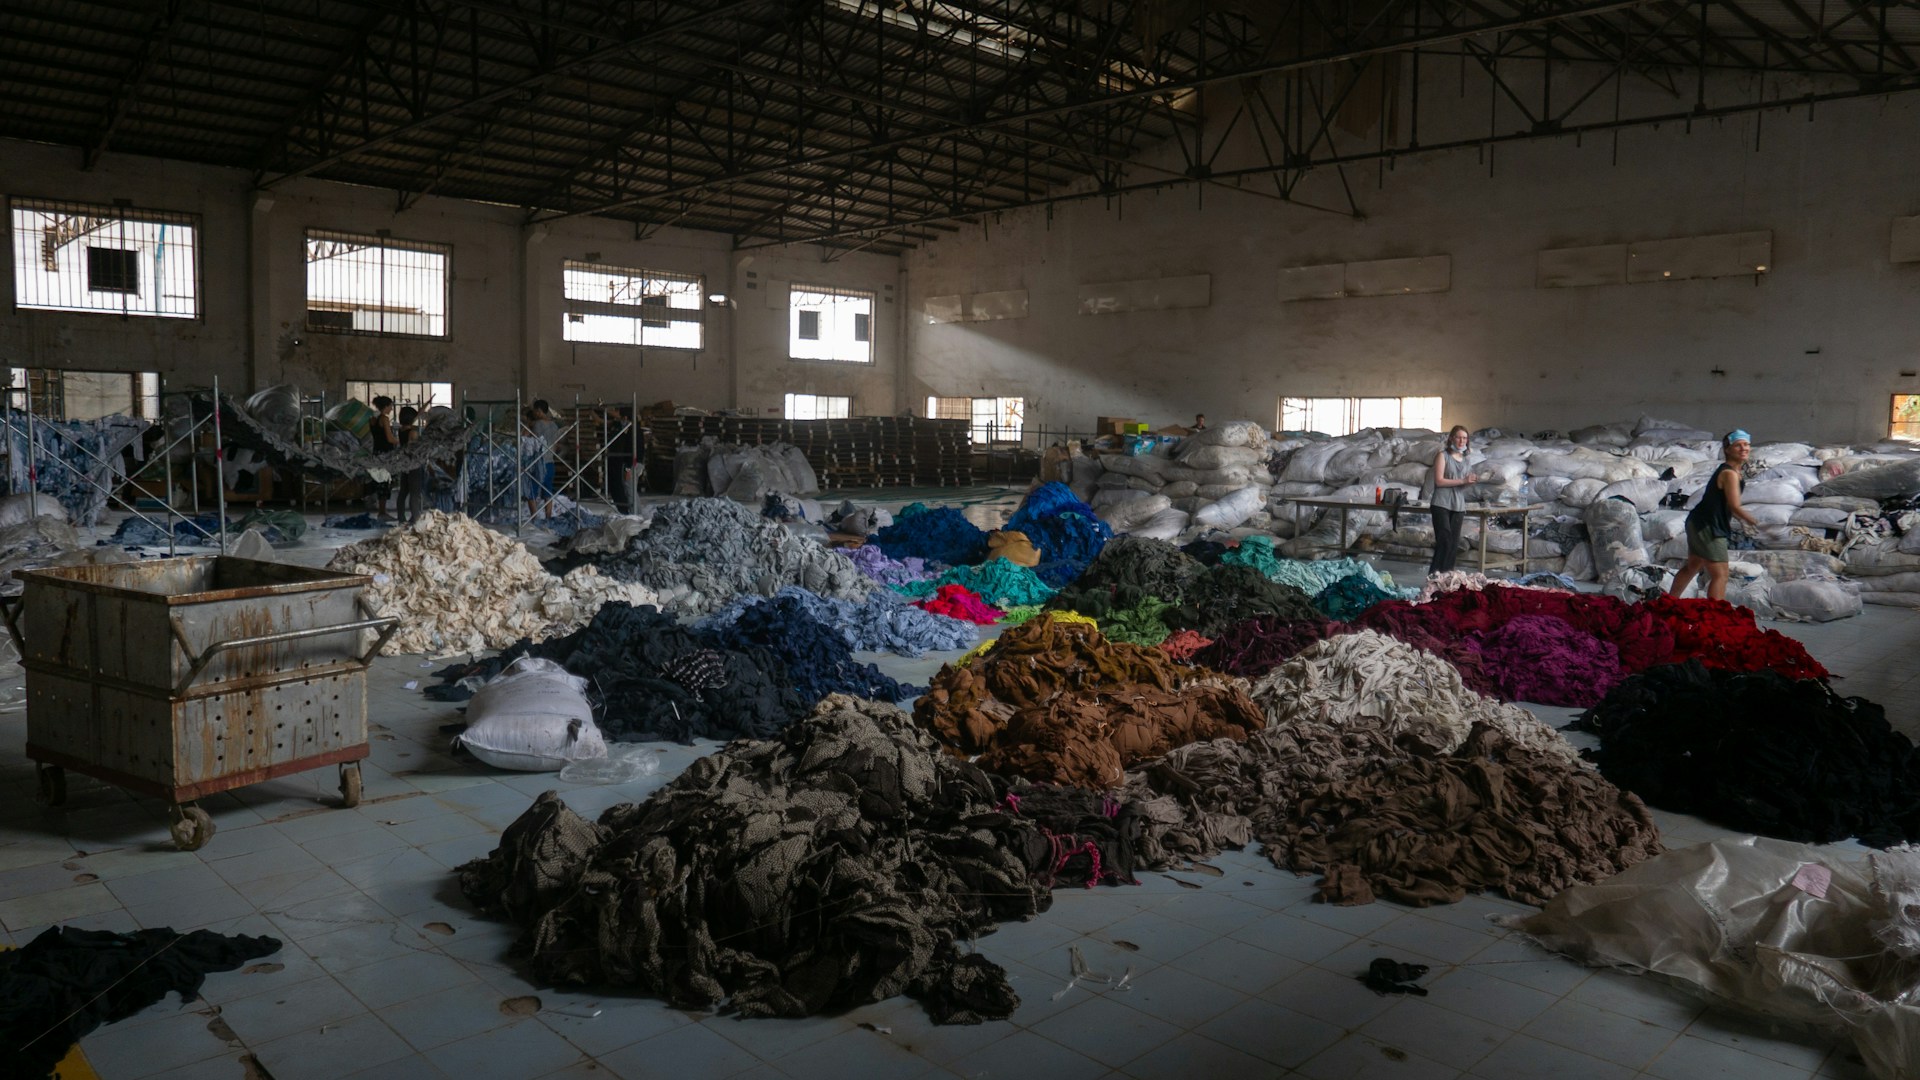
• France has introduced a new environmental tax on fast-fashion products, aimed at reducing the environmental impact of the textile industry. • The measure took effect on September 1, 2026, with charg…